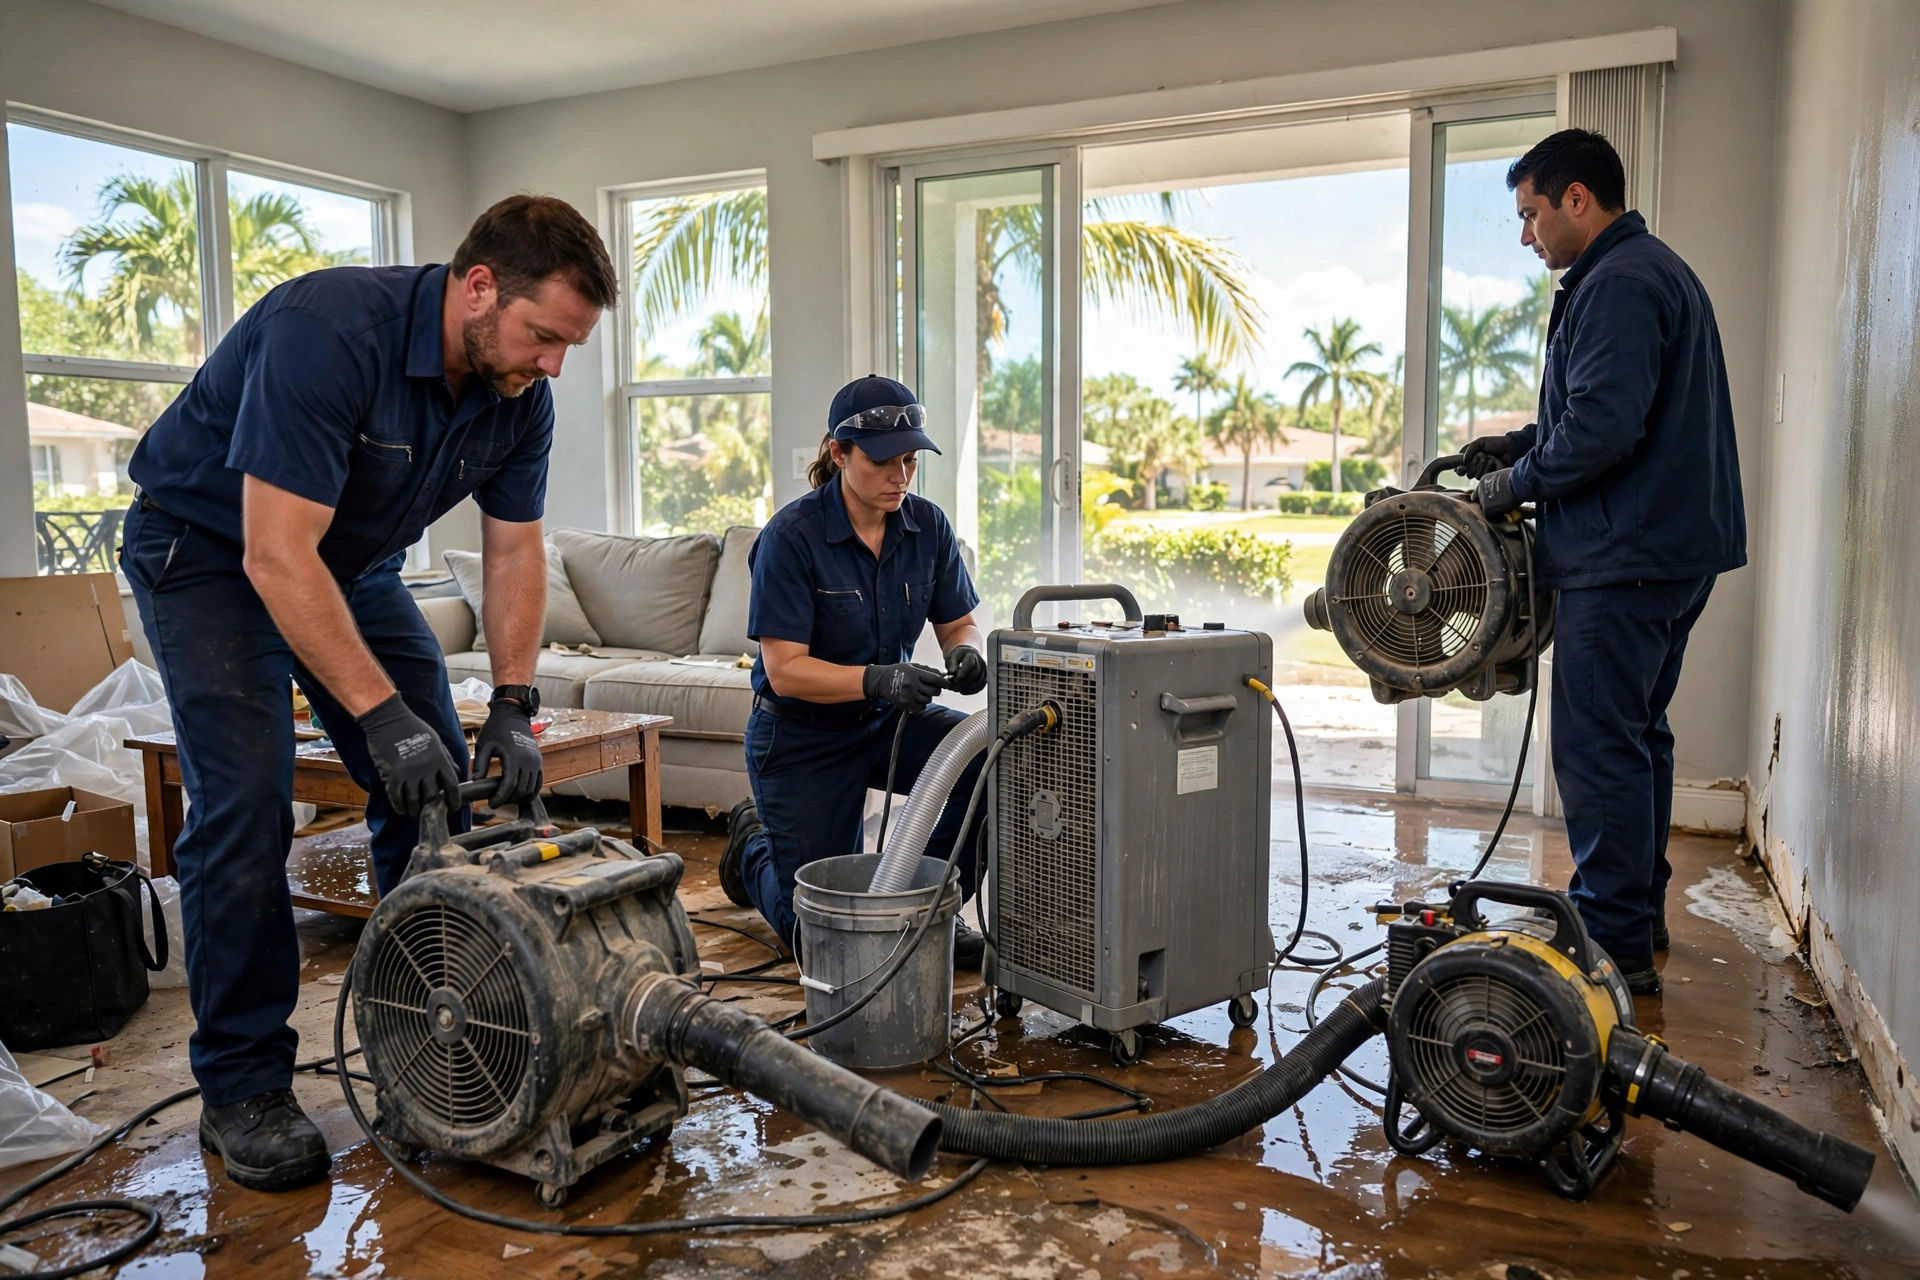
Water damage insurance claim documentation with photos and moisture logs in Florida

Water Damage Insurance Claims Assistance in Florida

Your claim is won or lost in the documentation. We photograph everything, log moisture readings and scope in Xactimate, then work directly with your adjuster.

Documentation wins claims

What adjusters actually need from a water loss

Quick answer

Water damage claims are decided by evidence: photos of the source and spread, moisture meter readings proving what was wet and what was dried, an itemized scope of the mitigation and repair work, and a timeline of when everything happened. DryOut Inc builds this file automatically on every job: pre-work photos, daily drying logs, final verification readings and an Xactimate scope, the estimating format most Florida carriers and adjusters work in. We cannot guarantee your claim will be approved, but we can guarantee your adjuster gets a complete, professional file.

Most denied or underpaid water claims fail on the same grounds: no proof of when the damage happened, no proof of what was actually wet, or no proof that the work performed was necessary and priced fairly. Homeowners are asked to remember details weeks later and to price work they have never bought. That is not a fair fight, and it is why documentation starts on our first visit, not after the work is done.

Our role is documentation and coordination, not representation. We are your restoration contractor, and we speak the adjuster's language: line items, moisture logs and IICRC references. We do not negotiate your settlement or promise outcomes. What we do is make the factual record so strong that the legitimate parts of your claim are hard to dispute.
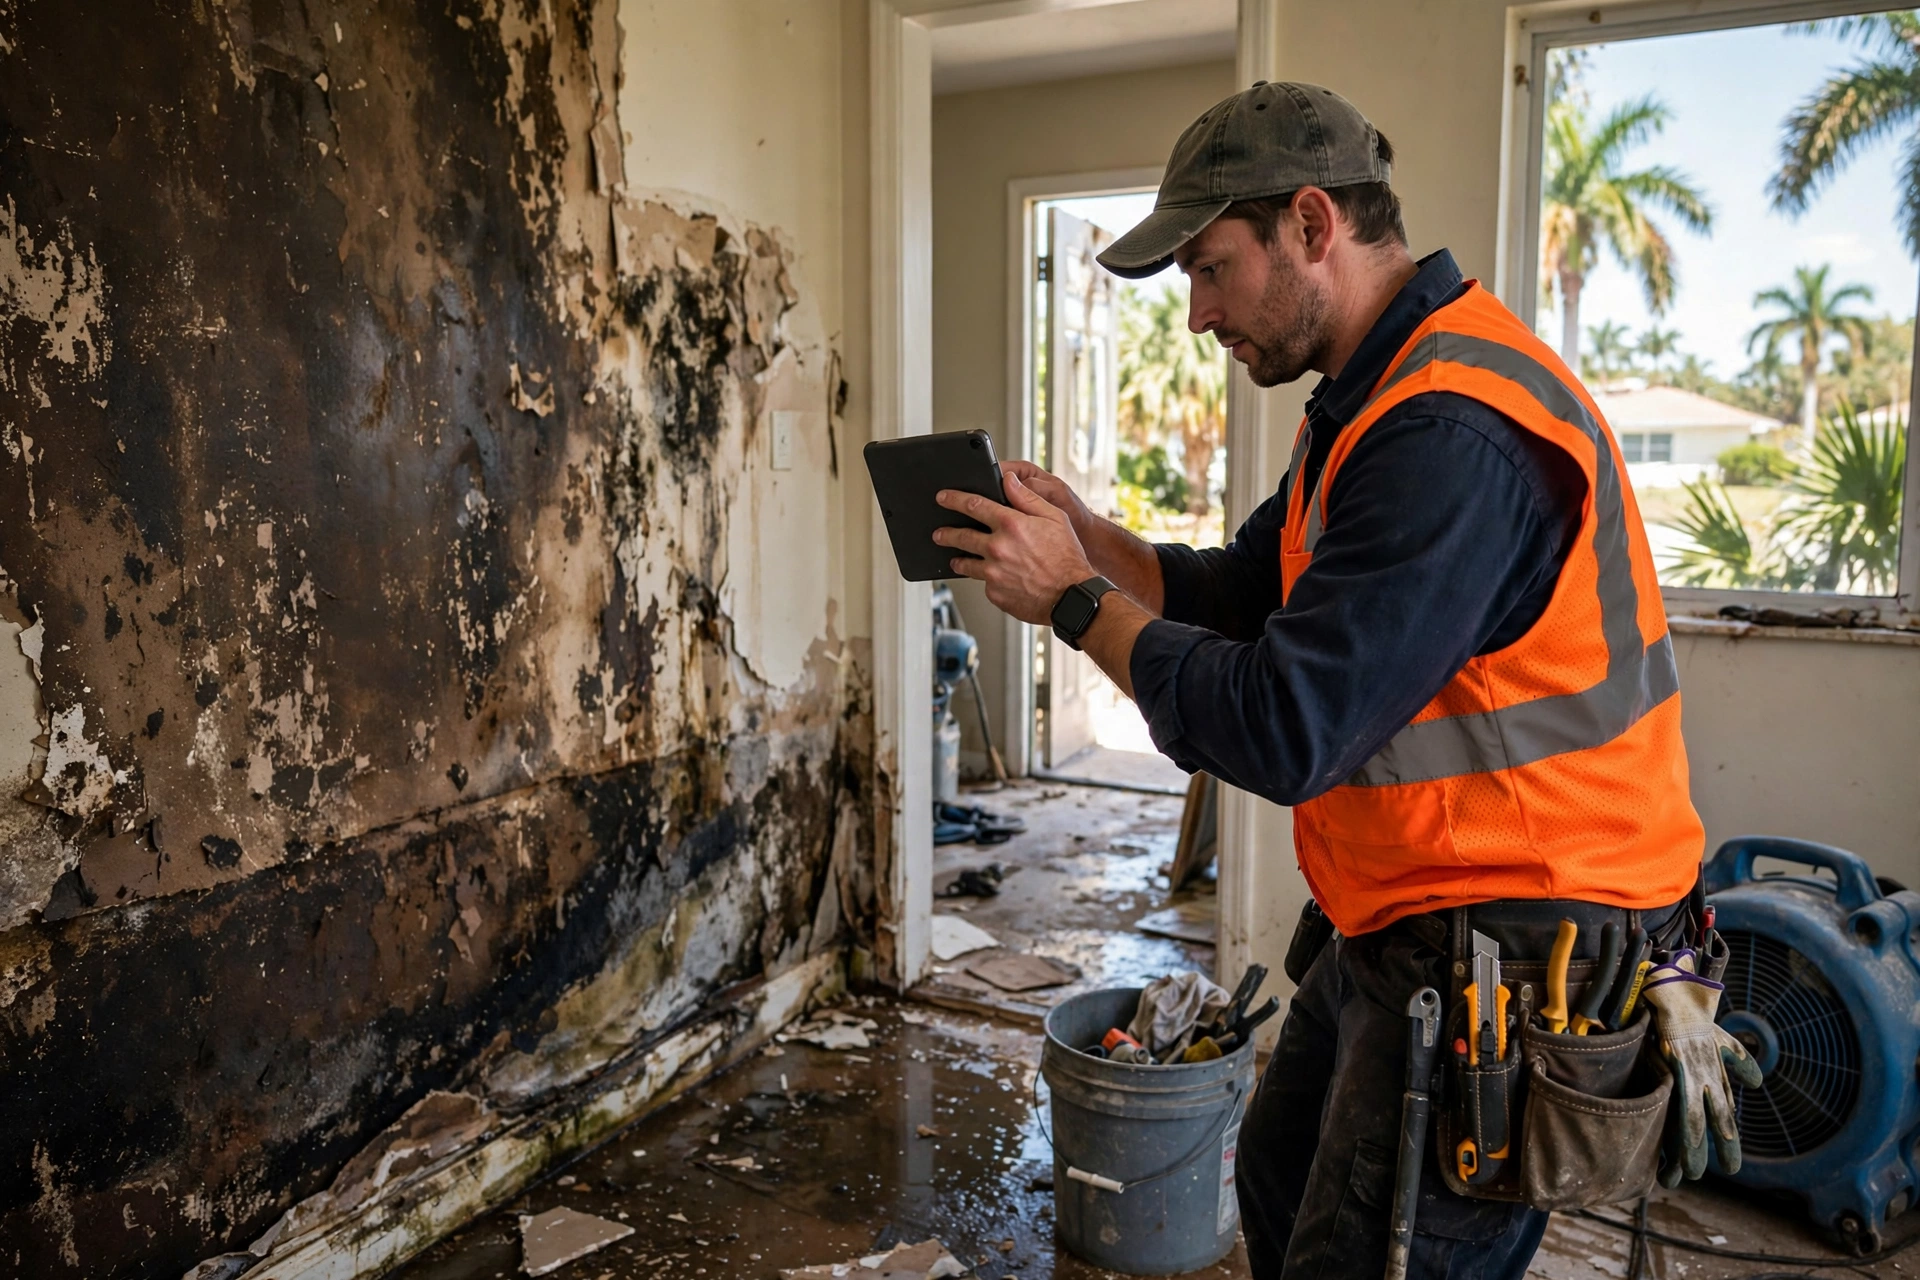
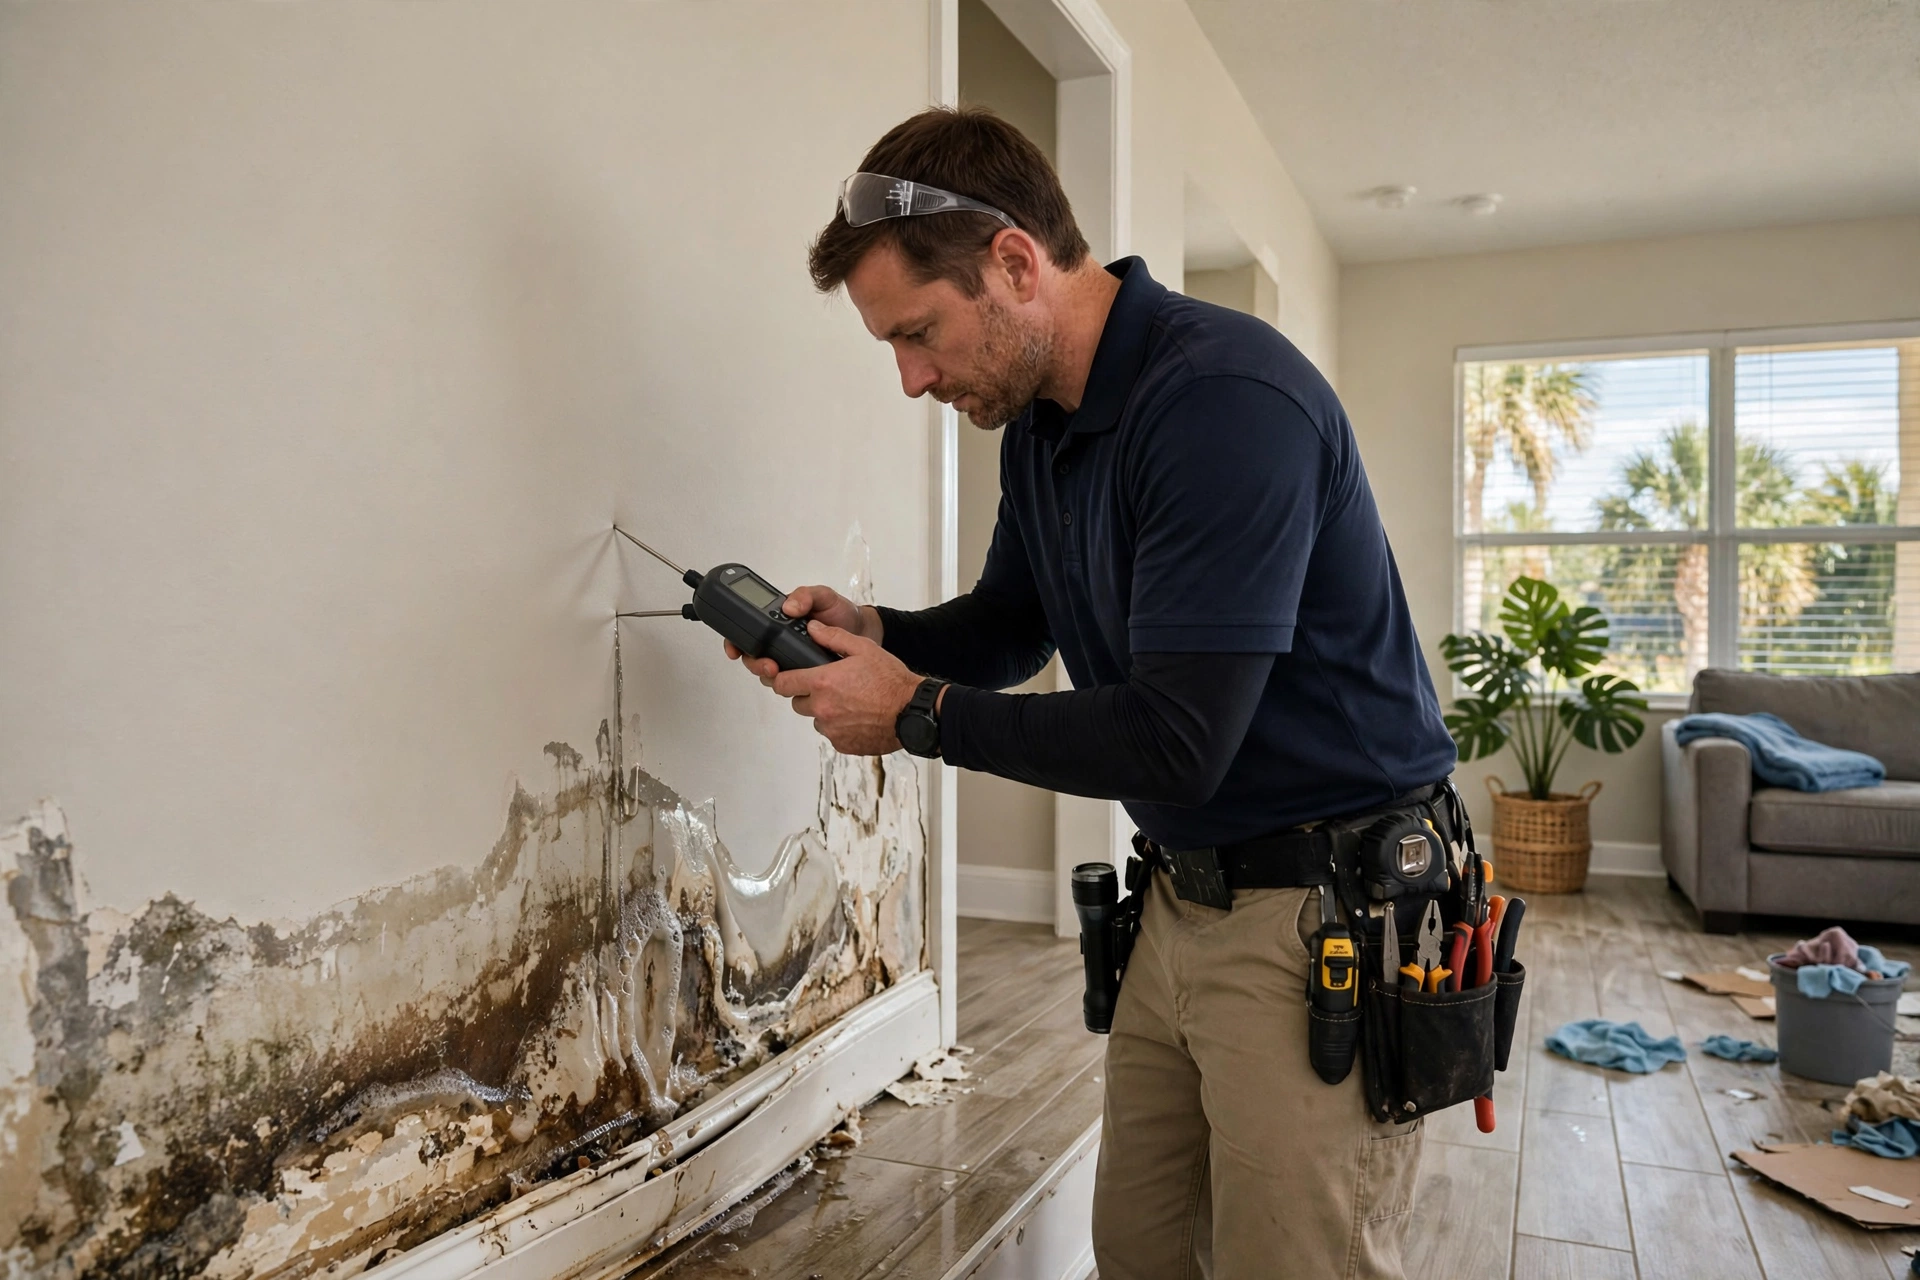
Technician documenting water damage with moisture readings for an insurance claim in Florida
Every reading and photo becomes part of your claim file
Florida rules that matter

Water damage claim rules every Florida homeowner should know

Florida has specific laws and deadlines that shape how water claims work. This is general information, not legal advice.

One-year notice deadline

Florida generally requires notice of a property damage claim within one year of the date of loss. Supplemental claims have an 18-month window. Do not sit on water damage hoping it dries; the clock is running from the day it happened.

Assignment of Benefits ban

Florida banned Assignment of Benefits agreements for property insurance policies issued or renewed after January 1, 2023. You generally can no longer sign your claim benefits over to a contractor. Any company asking you to sign an AOB on a current policy is asking for something the law no longer allows.

Sudden vs. gradual

Most Florida policies cover sudden and accidental water damage, like burst pipes, but exclude damage from long-term leaks, seepage and maintenance neglect. This is why fast response and clear documentation of when the event occurred protect your coverage position.

Mitigation is required

Your policy almost certainly requires you to mitigate further damage, meaning you must take reasonable steps to stop the loss from growing. Professional extraction and drying is the textbook definition of mitigation, and delaying it can give the carrier grounds to reduce payment.

Hurricane deductibles differ

Windstorm and hurricane losses may fall under a separate, percentage-based hurricane deductible rather than your standard deductible. Know which deductible applies before the adjuster visit so the numbers are not a surprise.

Document before cleanup

Photograph the source, the spread and the conditions before anything is moved or removed, then photograph each stage of the work. Our crews do this systematically, but your own phone photos from the first minutes are valuable evidence too.

The file we build

Inside your DryOut Inc claim documentation package

Every job file contains the same evidence set, organized for adjuster review.

DocumentWhat it provesWhen it is created
Pre-work photo setSource, spread, water lines and pre-existing conditionsFirst visit, before work begins
Moisture mapping and readingsExactly which materials and areas were wet, and how wetDay one, then daily during drying
Drying logEquipment placed, daily readings, adjustments madeUpdated every monitoring visit
Final verification readingsThe structure reached documented dry standardsAt drying completion
Xactimate scopeLine-item estimate in the format carriers useWith the written scope, updated as needed
Material disposal recordsWhat was removed and why it could not be savedDuring mitigation, photographed
Final walkthrough sign-offYou accepted the completed workAt job close

Xactimate is the estimating platform most Florida insurers and adjusters use. Scoping in the same format removes pricing-format disputes before they start.

Working with your adjuster

How adjuster coordination works

  1. You open the claimCall your insurer and report the loss. Note the claim number and the adjuster's name and contact details.
  2. We share the documentationWith your permission, we provide the adjuster our photo file, moisture logs and Xactimate scope, and we are available for the adjuster's inspection visit.
  3. Scope alignmentIf the adjuster's scope differs from ours, we walk through the discrepancies line by line with readings and photos, the language adjusters work in.
  4. Work proceeds with approvalRestoration moves forward on the agreed scope. Supplements for hidden damage found during work are documented the same rigorous way.
DryOut Inc coordinating a water damage insurance claim in Florida
Direct, professional communication with your adjuster

Honest about what we cannot do: We cannot promise your claim will be approved, and we will not tell you otherwise. We are not public adjusters or attorneys, and we do not negotiate settlements. What we promise is accurate documentation, direct communication with your adjuster, and work scoped to what the property actually needs. If your claim is denied or underpaid, the file we built is exactly what a public adjuster or attorney needs to evaluate your options.

FAQ

Insurance claim FAQs

Possibly. Florida insurers can consider claim history at renewal, and multiple water claims in a few years draw particular scrutiny. This does not mean you should skip filing a legitimate large claim, but it is one reason the free inspection matters: if the damage is small enough to handle out of pocket, we will tell you.

An Assignment of Benefits let a homeowner sign insurance claim rights over to a contractor, who then dealt with the insurer directly. Florida banned AOBs for policies issued or renewed after January 1, 2023, following widespread abuse. Today, you stay in control of your claim, and legitimate contractors document and coordinate without needing your benefits signed over.

Generally one year from the date of loss for the initial notice, with 18 months for supplemental claims. Practically, file as soon as the emergency is stabilized. Late notice is one of the most common reasons carriers dispute otherwise valid claims.

Get the denial in writing with the specific policy language cited. Many denials turn on facts that better documentation can address, such as whether the loss was sudden versus gradual. The photo file, moisture logs and timeline we built are exactly what a public adjuster or attorney needs to review your options.

Yes, with your permission. We share our documentation file, make ourselves available for the adjuster inspection, and reconcile scope differences line by line using readings and photos. You stay in control of all decisions and communications about your claim.

Your claim deserves a professional file.

Let us build the documentation your adjuster needs, from the first photo to the final moisture reading.

Call 24/7: (607) 300-1334